Roofing financing available in Desert Hot Springs, CA today looks a lot different than it did even two years ago, with a formerly popular property-tax program now defunct and new administrators taking its place. Most homeowners don't keep $12,000 to $20,000 sitting in savings for a roof failure, so the financing question usually comes before the contractor call. This guide breaks down what's actually available right now, not what used to be available, so you can match the right product to your situation.
Start With the Right Financing Framework
The right choice comes down to four things:
- How much home equity you've built
- Your credit profile
- How fast the work needs to happen
- Whether insurance might cover part of the cost
Desert Hot Springs sits in Riverside County, which matters more than most homeowners realize once you get to the property-tax-based financing option covered below.
Get a Local, Written Estimate First
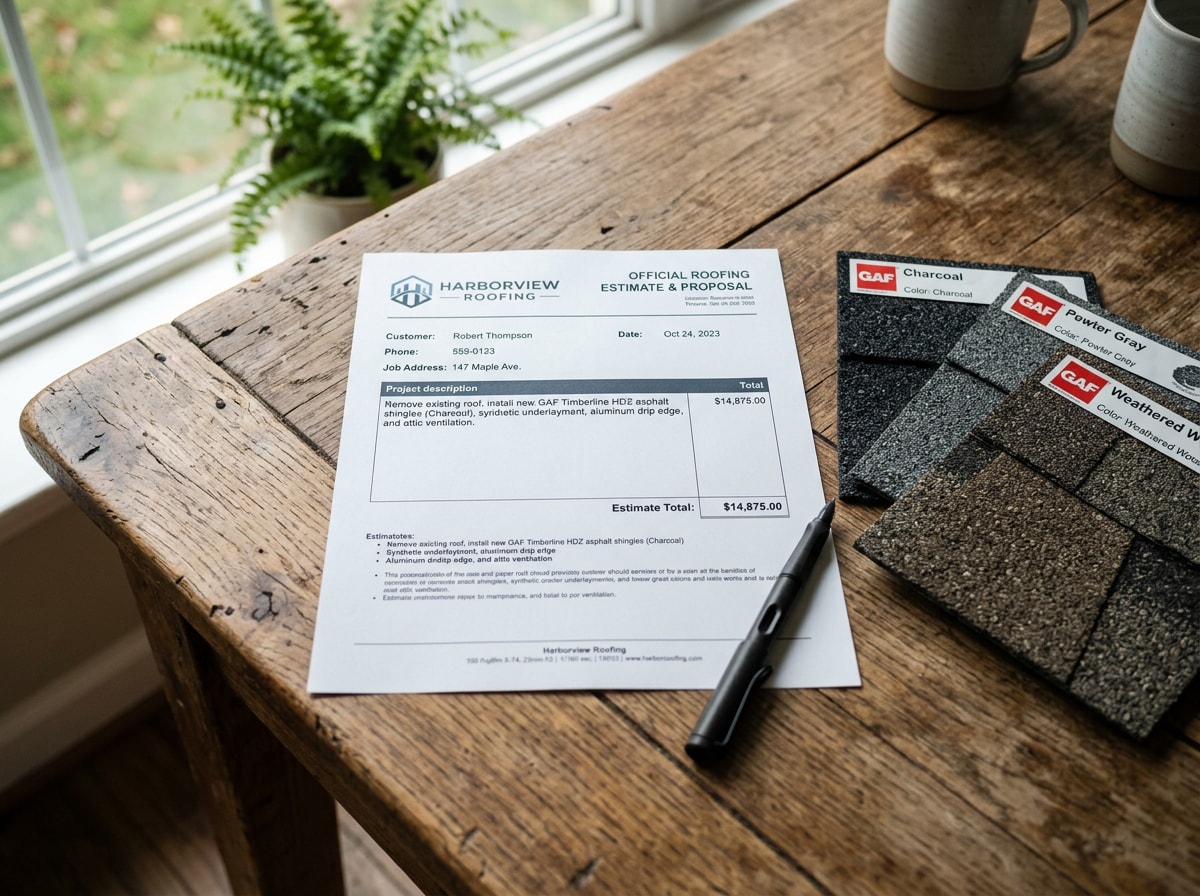
Get an itemized estimate from a local roofer before shopping for financing. Borrowing against a national average roof replacement cost instead of an actual local quote almost always leads to over- or under-borrowing.
Desert climate roofs aren't standard jobs. Heat-reflective shingles or coatings, upgraded attic ventilation, and underlayment rated for sustained triple-digit heat all push Desert Hot Springs pricing above generic online calculators. Lock in a real number first, then match it to a loan.
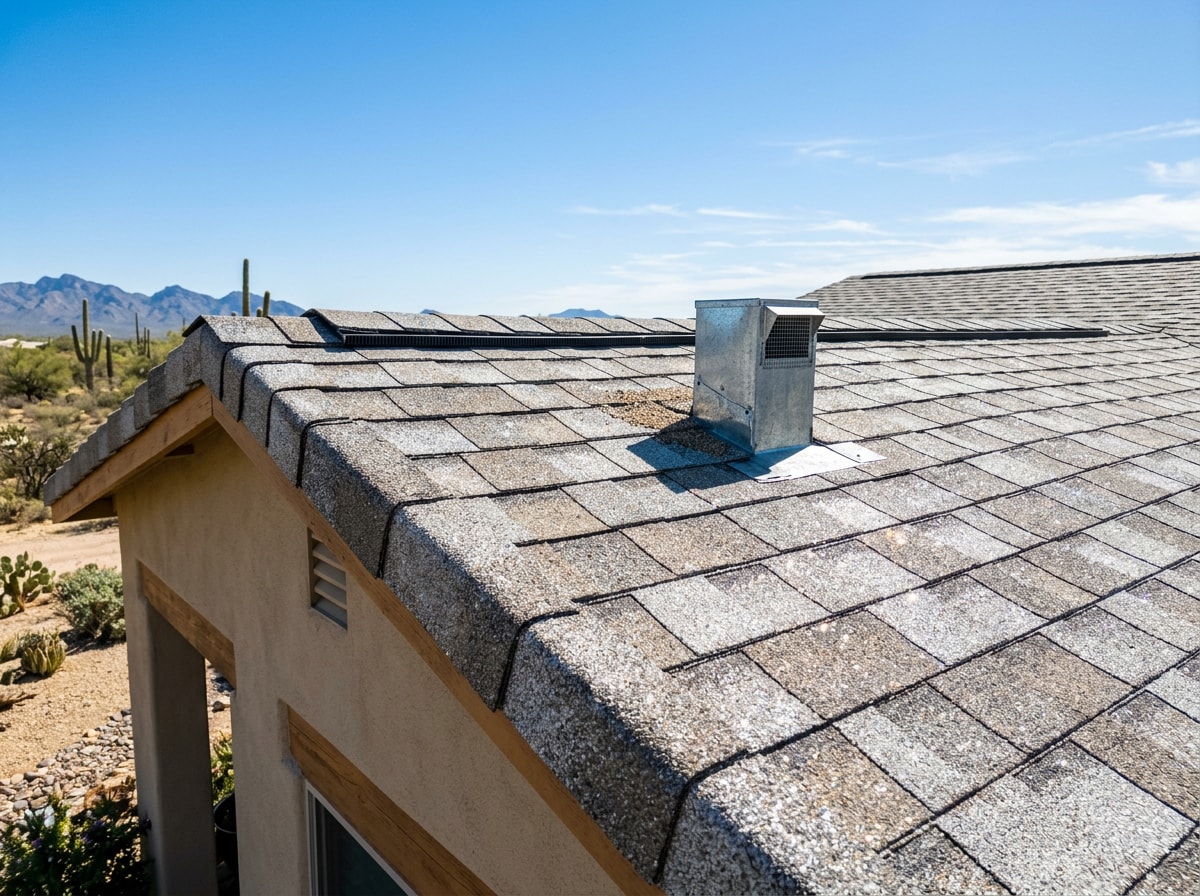
Before comparing lenders, it helps to see what a typical project actually involves. Our roofing services page covers installation, repair, inspection, and replacement so you know what you're pricing out.
Home Equity Loan or HELOC
A home equity line of credit (HELOC) and a home equity loan both borrow against your home's value, but they work differently. A HELOC is a revolving credit line with a variable rate you draw from as needed, while a home equity loan pays out a lump sum at a fixed rate from day one.
Most lenders require you to retain roughly 20% equity after borrowing, and closing typically takes two to four weeks, slower than a personal loan but usually cheaper. Interest on either product may be tax-deductible if the funds go toward home improvement, but that depends on your overall tax situation. Confirm the details with a tax advisor before assuming a deduction applies.
Personal Loan
A personal loan is an unsecured loan: no home equity, no collateral, just your credit and income backing the borrowing. That makes it appealing if you're renting part of the year, haven't built much equity, or simply don't want a lien tied to the house.
Approval is also noticeably faster than a HELOC, sometimes within a day or two, which matters if a leak needs fixing now. The tradeoff is rate sensitivity: strong credit gets a competitive rate, while a thinner credit file can push the APR considerably higher.
Contractor (In-House) Financing
Many roofing companies offer financing through a third-party lending partner right at the point of sale. These programs often advertise 0% financing for an introductory period, which can be genuinely useful if you can pay the balance off before that window closes.
The risk is a deferred-interest clause. Miss the payoff deadline, even by a few dollars, and some plans charge interest retroactively on the entire original balance. Before signing anything, ask the contractor to put the full payoff math in writing, not a verbal promise.
PACE Financing in Desert Hot Springs: What's Actually Active Right Now
Here's where most roofing-finance articles get outdated fast. PACE (Property Assessed Clean Energy) financing attaches the loan to the property itself, not to you personally, and it's repaid as a line item on your property tax bill. If you sell before it's paid off, the balance typically transfers to the new owner.
The HERO brand, which pioneered Riverside County PACE lending years ago, is no longer taking new applications. HERO was a California PACE assessment program, now inactive for new financing. That doesn't mean PACE itself disappeared locally. Other administrators have stepped in, and at least one, Home Run Financing, provides PACE financing in over 360 California cities and towns, approved in more than 340 municipalities and 46 counties , with Desert Hot Springs listed by name among the Riverside County communities served , alongside nearby Palm Springs, Palm Desert, and Indio.
PACE-enabling legislation is active in 40 states plus D.C., but residential PACE is currently only offered in California, Florida, and Missouri. That narrow footprint is exactly why Desert Hot Springs homeowners are in a better position than most of the country if PACE fits their situation.
One more thing worth knowing before you sign: a new CFPB rule applying ability-to-repay requirements to residential PACE financing takes effect March 1, 2026 , which should mean clearer underwriting standards than the industry has had in the past. Approval still leans more on home equity and property tax payment history than on a traditional credit score, which opens the door for homeowners who might not qualify elsewhere.
Government Programs That Help Pay for a Roof
Beyond private loans and PACE, two federal programs exist for homeowners who don't qualify for, or simply want to avoid, conventional credit-based financing.
USDA Section 504 Home Repair Loans and Grants
USDA Section 504 loans top out at $40,000, and grants are capped at $10,000, with loans and grants combinable for up to $50,000 in assistance. Loan terms run 20 years at a fixed 1% interest rate, which is one of the lowest-rate roof financing paths available anywhere.
Eligibility hinges on income limits and USDA's rural-area designation, and not every address in or near Desert Hot Springs will qualify automatically. You must be the homeowner and occupy the house, be unable to obtain affordable credit elsewhere, and fall under the county income limit; grant eligibility also requires being age 62 or older. Check your specific address through the USDA Single Family Housing Repair Loans & Grants program page before assuming you're covered.
FHA Title I Property Improvement Loans
HUD insures private lenders against loss on property improvement loans, and improvements must substantially protect or improve the basic livability or utility of the property. Unlike FHA mortgage products, this program has no HUD-mandated minimum credit score, though lenders still pull credit and review the borrower's history before approving a loan.
Single-family loan amounts are generally capped well below a full roof replacement budget, so Title I tends to work best for partial repairs or as a supplement to another financing source. See the official HUD Title I Insured Programs page for current terms.
When Insurance Helps Offset the Cost
Homeowners insurance isn't financing in the lending sense, but it can offset the cost when damage is covered. Homeowners insurance policies typically cover roof damage resulting from a covered peril, such as wind, hail, or falling trees.
Desert climates rarely see hail, but they see something just as damaging over time: sustained UV exposure that degrades shingles and membranes years before their rated lifespan. That kind of wear-and-tear is typically excluded from a standard claim, since insurers treat it as a maintenance issue rather than a sudden event. If you're not sure whether your roof's condition could affect a future claim, a roof inspection gives you documentation either way. More detail on how insurers draw that line is available from the Insurance Information Institute.
Financing Comparison at a Glance
| Option | Rate Profile | Term | Credit/Collateral | Approval Speed | Best Fit |
|---|---|---|---|---|---|
| HELOC / Home Equity | Lower, often variable | 10–20+ years | Home equity, credit check | 2–4 weeks | Full-time residents with built-up equity |
| Personal Loan | Moderate to high | 3–7 years | None, credit-based | 1–3 days | Renters-turned-owners or second-home buyers needing speed |
| Contractor Financing | 0% promo or deferred interest | Varies | Soft/hard credit check | Same day | Homeowners confident they'll pay off the promo window |
| PACE | Fixed, tied to tax bill | Up to 20+ years | Property equity and tax history | 1–3 weeks | Fixed-income retirees and owners light on credit history |
| USDA Section 504 | 1% fixed (loan) | 20 years | Income and rural-area based | Weeks, funding-dependent | Very-low-income homeowners in eligible rural areas |
| FHA Title I | Varies by lender | Varies | No HUD minimum credit score | Days to weeks | Smaller repairs or as a supplement to another loan |
Fixed-income retirees common throughout the Coachella Valley often lean toward PACE since it avoids a traditional monthly payment, while seasonal or second-home owners sometimes prefer a personal loan to avoid tying debt to a property they don't occupy year-round.
What to Avoid
Charging a roof to a standard credit card feels fast, but the math rarely works out. At typical credit card APRs, a $15,000 balance paid down slowly can generate thousands of dollars in extra interest compared with almost any financing option on this page.
Deferred-interest contractor promotions carry a similar trap. The 0% period looks great until a missed deadline triggers interest charged retroactively across the full original balance, not just the remaining amount. For more on how roof replacement costs break down before you commit to any loan, our roofing replacement guide for Palm Desert walks through typical line items, and our roofing terminology guide for Desert Hot Springs helps you read a contract before you sign it.
Before signing anything, request a free written estimate so you know exactly what you're agreeing to and what it should cost.
FAQ
What's the cheapest way to finance a roof replacement?
A HELOC or home equity loan is typically the cheapest option because the loan is secured by your home, which lowers the lender's risk. The tradeoff is a slower approval timeline and the equity requirement.
Is PACE financing still available in Desert Hot Springs?
Yes, through current administrators even though the original HERO program stopped taking new applications. Confirm which PACE provider currently serves your specific address before signing a contract, since terms and fees vary by administrator.
What credit score do you need to finance a roof?
Personal loans generally need a score in the mid-600s or higher for competitive rates. Contractor financing tends to be more flexible, PACE weighs home equity and tax payment history over credit score, and FHA Title I has no HUD-set minimum, though individual lenders still review credit.
Can you finance a roof with bad credit?
Yes. Contractor financing, FHA Title I, and PACE are generally the most accessible paths since they weigh factors other than a standard credit score.
How long can you finance a roof for?
Terms vary: personal loans usually run 3 to 7 years, home equity products can stretch 10 to 20-plus years, and PACE can extend to 20 years or more depending on the administrator. Shorter terms mean higher payments but less total interest paid.
Does homeowners insurance cover a roof replacement?
Only if the damage comes from a covered peril like wind, hail, or fire. Gradual deterioration from UV exposure or age is treated as a maintenance issue and is almost always excluded.
Ready to see real numbers for your home? Request a free estimate and compare financing options against an actual local quote, or visit our homepage to see the full range of roofing and electrical services we offer across the Coachella Valley.